2 min read · Ralph Simeone, All In Roofing
Does Homeowners Insurance Cover Roof Damage in New Jersey?
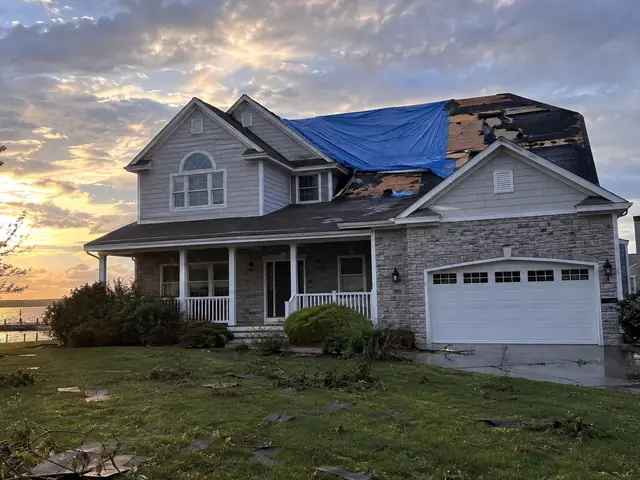
Usually, if the damage is sudden and accidental, like wind tearing off shingles, hail or a fallen tree, subject to your policy's terms and deductible. Homeowners policies generally don't pay for normal wear and tear, and the NJ Department of Banking and Insurance notes that all homeowners policies exclude damage caused by flood.
The short version
Homeowners insurance is built for sudden events, not for a roof that has simply aged out. Every policy is different, so your declarations page and policy wording are what count, but here is the general pattern in New Jersey. This is general information, not legal or insurance advice.
What's usually covered
- Shingles blown off or creased by a windstorm
- Hail damage
- A tree or large limb falling on the roof
- Fire and lightning
- Interior water damage that results from a covered roof loss
What's usually not covered
- Normal wear and tear. The NJ Department of Banking and Insurance (DOBI) lists it among common exclusions. Granule loss, curling and old age are maintenance.
- Flood. DOBI states that homeowners policies exclude water damage caused by flood. Flood coverage is a separate policy, for example through the National Flood Insurance Program.
- Neglect. Damage that grows because a known problem wasn't fixed can be disputed.
Deductibles that surprise people
Beyond your regular deductible, check for these two:
- Hurricane deductible. According to DOBI, many policies have one that applies only when the National Weather Service designates a hurricane and sustained winds of 74 mph are measured anywhere in New Jersey. It's often a percentage of your dwelling coverage (Coverage A), such as 1, 2, 5 or even 10 percent. On a home insured for $400,000, a 2 percent deductible is $8,000.
- Windstorm or hail deductible. An optional separate deductible, chosen as a fixed dollar amount or a percentage of Coverage A up to 10 percent.
Replacement cost vs. actual cash value
DOBI explains that homeowners policies typically pay replacement cost on the dwelling and actual cash value (value after age and condition) on personal property. Some policies settle roofs differently, especially older roofs, so read yours or ask your agent how a roof claim would be paid.
How to protect your claim
- Photograph damage from the ground right away, with dates.
- Make temporary repairs, such as a tarp, to prevent further damage, and keep receipts.
- Report the claim promptly and ask what your deductibles are.
- Get a written inspection from a registered roofer so you know what's storm damage and what's age.
If you have a dispute with an insurer, DOBI's consumer assistance office takes inquiries and complaints. For an honest look at whether your roof damage is storm-related, All In Roofing does free inspections: call or text 732-584-0700.